Master Your Money: A Better Budgeting Guide for Beginners
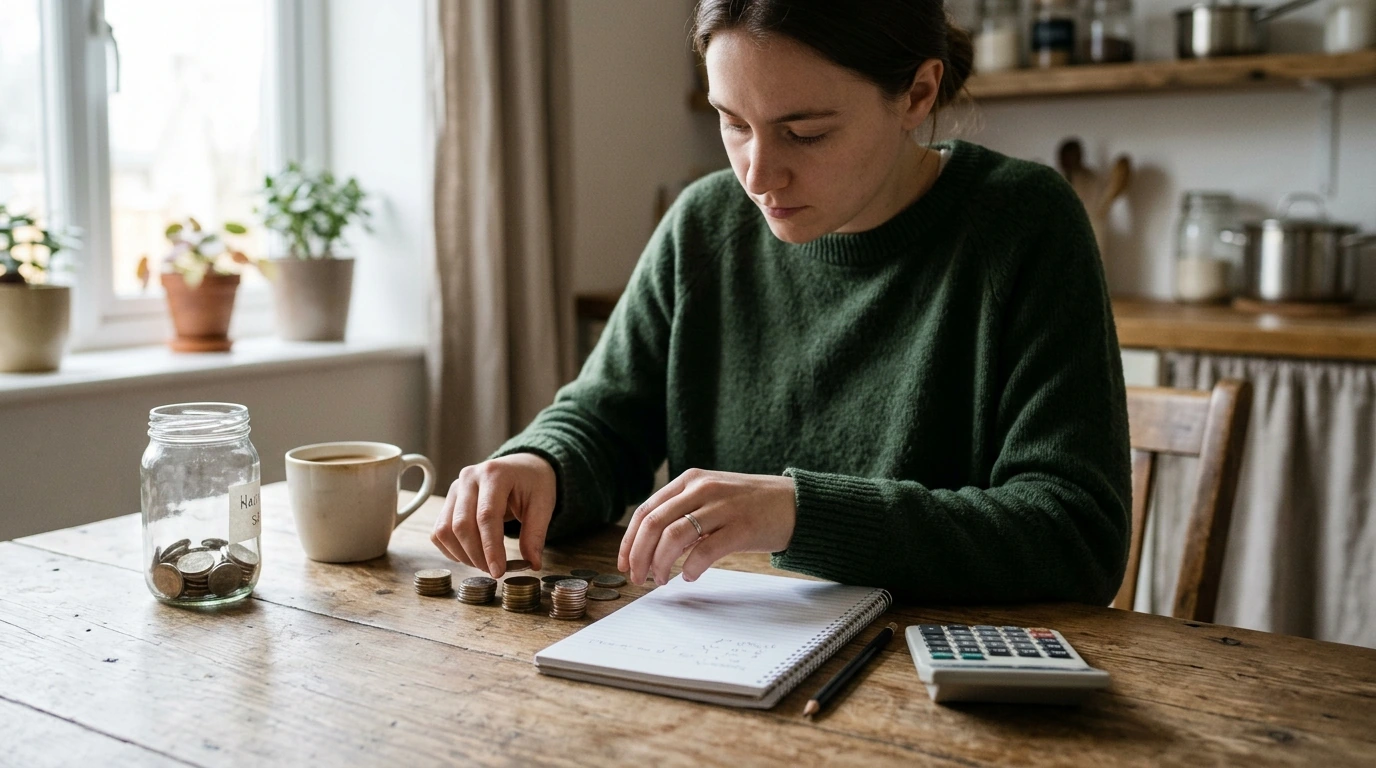
A budget gives your everyday spending a purpose. It helps you see what comes in, what needs to go out, and what you can put toward goals that matter to you. You don’t need a perfect plan to begin; you need a realistic picture of your money and a way to revisit it.
Our Master Your Money: The Better Budgeting Checklist offers beginners a starting point for organizing that picture. Pair it with your own bills and spending records to build a budget that fits your life.
Start With the Money You Have
Begin with your monthly take-home income: the money you receive after taxes and other deductions. Include reliable paychecks and other income you regularly receive. If you’re paid every two weeks, remember that two paychecks per month is not the same as your annual income divided by 12; decide how you’ll handle the extra-paycheck months rather than counting on them to cover every month’s bills.
If your income changes, use a conservative estimate based on recent lower-earning months. You can add money to the plan when it arrives, but starting with a cautious number makes it less likely you’ll commit money you haven’t earned.
Next, gather recent bills, bank and credit card statements, and receipts. Look for recurring payments as well as expenses that are easy to miss, such as subscriptions, annual fees, and occasional medical costs. The consumer.gov guide to making a budget offers a useful overview of tracking income and expenses.
Build a Budget You Can Use
List your essential expenses first, including housing, utilities, groceries, transportation, and insurance. Add required debt payments, then identify flexible spending such as entertainment and dining out. Finally, include savings goals, even if the amount is small. For bills that arrive less often than monthly, divide the expected cost by the number of months you have to save for it.
Subtract all planned spending and savings from your estimated monthly income. If the result is negative, your plan needs adjustment. Review flexible categories first, look for expenses you can reduce, and make sure essential bills and required payments remain visible. If you have money left over, give it a purpose, such as building savings or paying down debt.
The table below is an illustration, not a recommended allocation. Your housing costs, debts, income, and priorities may call for a different balance.
| Category | Example amount |
|---|---|
| Take-home income | $2,500 |
| Housing and utilities | $1,000 |
| Food and transportation | $500 |
| Debt payments | $300 |
| Savings | $200 |
| Other spending | $500 |
In this example, planned expenses and savings total $2,500, leaving $0 unassigned. “Other spending” would need to cover any costs not already listed, so it’s worth breaking that category down before relying on the plan.
Put the Better Budgeting Checklist to Work
Our beginner-focused Master Your Money: The Better Budgeting Checklist can help you organize the steps of a first budget. Set aside time with the checklist, your bills, and your account statements, then write down the amounts you want to plan for the coming month.
As you work, note any numbers you need to confirm, such as a variable utility bill or the due date for an annual payment. Use your best available estimate for now and update it when you have better information. The checklist is listed at $5.99; visit the product page to review the current details before purchasing.
Keep Your Budget Flexible
A budget is a working plan, not a test you pass or fail. Once a week, take a few minutes to compare recent spending with your category limits. You might notice that groceries are running high or that a subscription you forgot is still being charged. A short check gives you time to respond before the month is over.
At the start of each month, reset your plan around upcoming bills and expected income. Include special occasions, appointments, and less frequent expenses you know are approaching. If an unexpected expense appears, adjust another category where you can instead of abandoning the budget altogether.
Consider building an emergency savings habit with an amount you can afford, whether that’s a few dollars each payday or a monthly transfer. Consistency can help you prepare for expenses that don’t fit your usual plan. The Consumer Financial Protection Bureau’s emergency fund guide explains ways to start and maintain that cushion.
Take the Next Step
Choose one manageable action today: list your bills, review a recent statement, or decide on an affordable savings amount. You can build the rest of your plan one category at a time.
If you’d like to explore financial literacy beyond budgeting, our Money Moves: The Empowered Woman’s Guide to Financial Literacy is a related option. Our team encourages you to choose the resource that fits your immediate goals and the time you have available.
FAQ
How do I start a budget if my income changes each month?
Estimate your income conservatively using recent lower-earning months, and prioritize essential bills in your first plan. Revisit your budget as income arrives and assign any additional money to current needs or goals.
How often should I review my budget?
Check your spending briefly each week and do a more complete review each month before upcoming bills are due. Adjust sooner if your income or circumstances change.
What if my expenses are higher than my income?
Review flexible expenses for possible reductions and prioritize essentials and required payments. If you still can’t cover your obligations, contact your creditors or a reputable financial counselor to discuss your options.





Leave a comment